DeFi arbitrage has grown from a niche tactic used by a handful of on-chain traders into a multi-billion-dollar segment of crypto trading activity. Every day, thousands of arbitrage bots scan dozens of decentralized exchanges and centralized exchanges looking for price discrepancies on the same asset, and every day a meaningful amount of money changes hands because markets briefly disagree with themselves. This guide breaks down exactly how DeFi arbitrage works in 2026, which protocols and exchanges offer the best opportunities, how arbitrage bots are built, and what risks every trader needs to manage before deploying capital.
DeFi arbitrage is the practice of exploiting price differences for the same asset across decentralized exchanges — and sometimes between decentralized and centralized exchanges — to lock in a low-risk profit. Because liquidity is fragmented across hundreds of automated market makers (AMMs), order book DEXs, and Layer 2 networks, the same token pair rarely trades at exactly the same price everywhere at the same moment. A trader who buys an asset where it is cheap and simultaneously sells it where it is expensive captures the spread as profit, minus fees and gas costs.
Unlike traditional securities arbitrage, which depends on regulated market makers and centralized clearing, DeFi arbitrage happens directly on public blockchains. Anyone with a wallet, some starting capital, and the right tooling can participate — no broker, no KYC gate, no securities license required. This permissionless structure is a core reason arbitrage opportunities in DeFi remain abundant even as the market matures: new liquidity pools, new chains, and new exchanges are launched constantly, and each one introduces fresh price discrepancies before the market fully arbitrages them away.
At its core, every arbitrage strategy in DeFi reduces to the same formula: identify a price gap for the same asset across two or more venues, execute both legs of the transaction fast enough that the gap doesn't close first, and make sure the expected value of the trade exceeds the combined fees, slippage, and gas costs. The faster and cheaper the execution, the more arbitrage opportunities become profitable — which is exactly why most serious DeFi traders now rely on automated arbitrage bots rather than manual trading. This fast-paced, algorithmic style of trading has become the default mode of crypto trading for anyone serious about capturing arbitrage opportunities at scale.
Arbitrage existed long before DeFi — traders have exploited price differences between centralized exchanges (CEX) for over a decade. This kind of cross-exchange trading predates crypto entirely, going back to traditional finance arbitrage desks. But the mechanics, risks, and opportunity set are meaningfully different once you move on-chain.
The biggest structural advantage of DeFi arbitrage is capital efficiency through flash loans: a trader can borrow a large amount of an asset with no upfront collateral, execute an arbitrage strategy across multiple pools in a single atomic transaction, repay the loan, and keep the profit — all without ever holding the underlying capital. This is simply not possible in CeFi arbitrage, where every leg of a cross-exchange trade requires pre-funded accounts on each venue.
On the other hand, CEX-to-CEX arbitrage typically enjoys tighter spreads and lower latency because centralized exchanges run off-chain matching engines that settle instantly. Many professional traders now run hybrid books that combine both worlds: DeFi-native strategies for flash loan and on-chain opportunities, plus traditional CEX arbitrage for liquid pairs like BTC/USDT and ETH/USDT where exchanges like Binance, OKX, and Bybit offer deep order books.
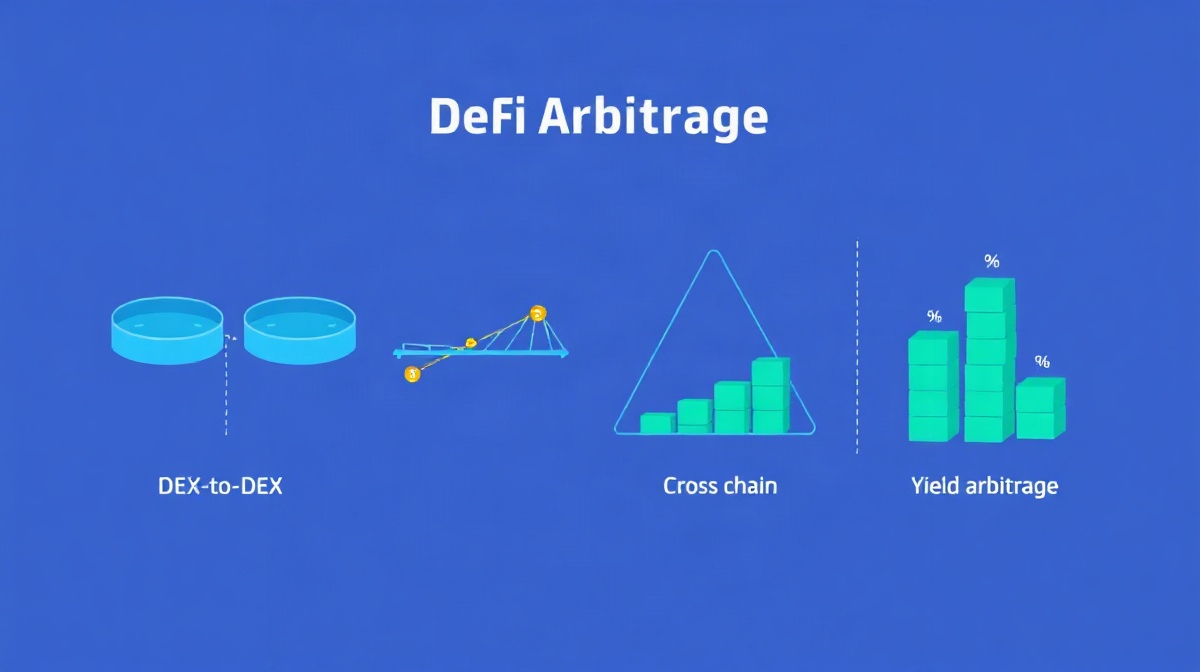
There isn't one arbitrage strategy — there are at least six distinct categories, each with its own risk profile, capital requirements, and technical complexity. Each trading approach below suits a different kind of trader, technical setup, and capital size.
The most common arbitrage strategy: buy an asset on one decentralized exchange where it's underpriced, sell it on another DEX where it's overpriced. A classic example is a price gap between Uniswap and SushiSwap on Ethereum, or between PancakeSwap and a smaller AMM on BNB Chain. Because AMMs price assets algorithmically based on pool reserves, large trades on one exchange shift the local price and create a temporary gap relative to other exchanges — exactly the kind of arbitrage opportunities bots are built to catch. This high-frequency trading style depends entirely on bot speed and low-latency infrastructure.
Here the trader exploits a price difference between a decentralized exchange and a centralized exchange. Because CEX order books often lead price discovery for major assets, a sudden move on Binance or Coinbase can take several seconds to fully propagate to on-chain liquidity pools. Traders who can execute fast enough capture that lag as arbitrage profit. This strategy requires accounts on both a CEX and a DEX-compatible wallet, plus pre-positioned capital on each side since you can't flash-loan funds into a centralized exchange. Day trading between a DEX and a CEX manually is nearly impossible at competitive speed, which is why most participants automate this trading flow entirely.
Triangular arbitrage exploits mispricing across three related trading pairs rather than a single asset across two exchanges. For example: convert ETH to USDC, USDC to DAI, and DAI back to ETH. If the implied exchange rate after three trades differs from your starting amount, there's a profit to be captured. This triangular trading technique is popular on single-exchange liquidity pools because it doesn't require bridging or moving funds between venues — everything happens within one DEX's routing paths.
As liquidity has spread across Ethereum, Arbitrum, Optimism, Base, BNB Chain, Polygon, Avalanche, and Solana, the same asset can trade at different prices on different chains simultaneously. Cross-chain arbitrage captures this gap by moving capital through a bridge, but it introduces latency and bridge risk that doesn't exist in single-chain strategies, making this cross-chain trading flow one of the more advanced setups in DeFi.
Yield arbitrage targets differences in lending rates, staking yield, or funding rates across protocols rather than spot price gaps. A trader might borrow an asset cheaply on one lending market and supply it for a higher yield on another, capturing the rate differential as returns. This overlaps heavily with funding-rate strategies on perpetual futures, covered in detail below, and treats yield generation as a trading discipline rather than passive income.
When a borrower's collateral value falls below a protocol's required ratio, lending markets like Aave or Compound open the position to liquidation. Liquidators repay part of the debt and receive the borrower's collateral at a discount — typically 5-10% below market value. This is a form of arbitrage because the liquidator immediately resells the acquired collateral asset on a DEX or CEX to realize the discount as profit — a core part of any serious DeFi trading operation during volatile markets.
Let's walk through a concrete example using a real token pair to show exactly how an arbitrage trade executes from start to finish.
Scenario: ETH/USDC trades at $3,180 on Uniswap V3 and $3,195 on SushiSwap, both on Ethereum mainnet — a $15 gap, or roughly 0.47%.
This atomic, single-transaction structure is unique to DeFi arbitrage and is the reason flash loan arbitrage bots can operate with essentially unlimited capital relative to their own balance sheet — see our flash loan arbitrage guide for a deeper technical breakdown.
Not every DEX is equally useful for arbitrage. Liquidity depth, fee structure, and chain coverage all determine how much real opportunity a given exchange offers across all major trading pairs.
Curve's low-slippage stablecoin pools make it a favorite for arbitrage between USDC, USDT, and DAI whenever one depegs even slightly. Aggregators like 1inch don't hold their own liquidity but route trades across dozens of exchanges simultaneously, which makes them a useful execution layer rather than a direct arbitrage target — many bots query 1inch's pricing API just to confirm the best available route before committing capital.
Manual arbitrage trading is effectively dead for anything beyond small, slow-moving opportunities. The real competition today happens between arbitrage bots, and understanding their architecture explains why speed and infrastructure matter more than trade size.
Before a transaction is confirmed in a block, it sits in the mempool — a public waiting area visible to anyone running a node. Arbitrage bots monitor the mempool in real time, looking for large pending swaps that will move an asset's price once confirmed. Spotting a large trade before it lands lets a bot position itself to profit the instant the price shifts, sometimes even bundling its own transaction to execute in the same block.
Rather than sending separate transactions for each leg of a trade, arbitrage bots deploy custom smart contracts that bundle the entire strategy — flash loan, swap on exchange A, swap on exchange B, loan repayment — into one atomic transaction. This guarantees the bot never ends up with partial exposure: either every leg executes profitably, or the whole transaction reverts and only the gas fee is lost — the kind of reliability that gives serious operators a real trading edge.
On Ethereum mainnet, gas costs can make or break an arbitrage strategy. Bots compete for block space by bidding gas prices, and the most sophisticated operators submit transactions through private relays like Flashbots to avoid front-running and reduce the chance of a failed transaction eating into profit. On Layer 2 networks and chains like BNB Chain or Polygon, lower gas fees mean smaller price gaps are still profitable, which is one reason arbitrage opportunities on L2s have grown so fast.
Top arbitrage bots run on dedicated nodes co-located near validator infrastructure to shave milliseconds off transaction propagation. Some elite trading teams run private mempools or use MEV-Share to capture value that would otherwise go to searchers — our MEV and arbitrage guide covers this in more depth for traders who want to go beyond basic bot setups.
One of the most reliable forms of arbitrage in 2026 doesn't depend on spot price gaps at all — it depends on funding rates in the perpetual futures market.
Perpetual futures contracts, offered by both DeFi protocols like dYdX and GMX and centralized exchanges like Binance and Bybit, use a funding rate mechanism to keep the futures price anchored to the spot price. When more traders are long than short, the funding rate turns positive and longs pay shorts; when sentiment flips, the opposite happens. A classic funding rate arbitrage strategy involves going long the spot asset while simultaneously shorting the equivalent amount in perpetual futures, collecting the funding rate payment as a market-neutral return regardless of which direction the underlying asset moves.
During periods of strong bullish sentiment, funding rates on BTC and ETH perpetual futures have spiked above 0.1% every 8 hours on major exchanges — an annualized yield well above 100% for traders willing to hold the hedged position. This is pure yield arbitrage: the trader isn't betting on price direction, just capturing the structural imbalance between spot and futures markets — a strategy now run by dedicated funding rate trading desks and crypto derivatives trading funds alike.
A related approach looks at lending rate differences across money markets. If Aave offers 3% yield on USDC deposits while a newer protocol offers 8% for the same asset, a trader can borrow at the lower rate and redeploy at the higher rate, provided the extra yield compensates for added smart contract risk. Combining spot-futures funding arbitrage with cross-protocol lending rate arbitrage lets sophisticated DeFi traders build a diversified book of market-neutral returns that doesn't depend on any single exchange or asset moving in a particular direction.
As total value locked has spread across a dozen major chains, cross-chain arbitrage has become one of the fastest-growing categories of arbitrage strategy — and one of the riskiest.
The basic mechanic is simple: the same asset, say USDC or ETH, trades at slightly different prices on Arbitrum versus Base versus Ethereum mainnet due to differences in local liquidity and demand. A trader bridges capital from the cheaper chain to the more expensive one, captures the spread, and bridges back. In practice, execution is far more complex than single-chain arbitrage for three reasons:
Because of these constraints, many professional cross-chain arbitrage desks maintain standing balances on 5-10 chains simultaneously, rebalancing periodically rather than bridging on every single trade. This reduces latency risk at the cost of tying up more capital across more venues, a tradeoff that defines most cross-chain trading desks today.
Arbitrage is often marketed as "risk-free," but every experienced DeFi trader knows that's never fully true. Here are the risks that matter most.
Traders who provide liquidity to AMM pools (rather than just arbitraging against them) face impermanent loss — the value lost compared to simply holding the underlying assets, caused by the pool's automatic rebalancing as prices diverge. Arbitrageurs themselves don't hold LP positions typically, but understanding impermanent loss explains why liquidity providers demand fees high enough to compensate, which in turn affects how wide arbitrage opportunities need to be before they're worth capturing.
Every flash loan, every swap, every lending interaction runs through smart contract code that could contain bugs or be exploited. Even audited, battle-tested protocols like Aave and Uniswap have had incidents elsewhere in the ecosystem. Diversifying which protocols a bot interacts with, and avoiding unaudited or newly launched exchanges no matter how attractive the yield, reduces this exposure.
The price you see when you submit a transaction isn't always the price you get once it confirms. Large trade sizes relative to pool depth cause slippage that can erase an otherwise profitable arbitrage opportunity. Bots must model expected slippage on both legs of a trade before committing, and set a minimum acceptable output to avoid loss if conditions shift mid-transaction.
Every leg of an arbitrage transaction carries fees: swap fees charged by the exchange (typically 0.01%-0.3% per trade), flash loan fees (usually 0.05%-0.09% of the borrowed amount), and gas fees paid to network validators. On a volatile day, gas fees alone can consume the entire margin on a marginal trade. Successful arbitrage bots build fee estimation directly into their profitability calculations rather than treating fees as an afterthought — a trade that looks profitable on raw price difference can easily turn negative once every fee is accounted for.
Traders who use leverage or borrow against collateral to scale their arbitrage strategy face liquidation risk if the collateral asset's value drops sharply. Maintaining a healthy crypto collateral ratio with buffer room is essential for every trading operation, especially for strategies that hold positions longer than a single atomic transaction, such as funding rate arbitrage. Sound risk management is what separates a professional trading operation from a gambling habit.
Running a competitive arbitrage operation in 2026 requires more than a wallet and some capital — it requires real-time data and monitoring infrastructure.
New traders often start by using an arbitrage calculator to model expected returns on a given trade size before writing any bot code, which is a far cheaper way to validate a strategy's assumptions.
Every crypto trading transaction tied to an arbitrage trade is a taxable event in most jurisdictions, and the frequency of trades is exactly what makes DeFi arbitrage tax reporting complicated. In the US, each swap — even the two legs of a single atomic arbitrage transaction — is generally treated as a disposal of one asset and acquisition of another, triggering capital gains or losses calculated against the dollar value at the time of the transaction.
High-frequency arbitrage bots can generate thousands of taxable transactions per month, which makes manual tracking impractical. Most active traders rely on crypto tax software (Koinly, TokenTax, CoinTracker) that ingests wallet addresses and automatically calculates gains across every transaction. Flash loan transactions add another wrinkle: because the loan and repayment happen within the same block, tax treatment generally focuses only on the net profit realized, not the full borrowed amount, but traders should confirm specifics with a qualified tax professional given how unsettled DeFi-specific guidance remains in many countries.
It's also worth noting that regulators in several jurisdictions are increasingly scrutinizing whether certain DeFi yield products resemble unregistered securities. While arbitrage trading itself is generally treated as ordinary trading activity rather than a securities offering, traders engaging in yield arbitrage through lending protocols or staking derivatives should stay aware of evolving securities law interpretation, particularly in the US where the SEC has pursued several DeFi-adjacent enforcement actions.
The short answer: yes, but the easy money is gone. In 2020-2021, simple DEX-to-DEX arbitrage bots running basic scripts could capture meaningful arbitrage opportunities with minimal competition. By 2026, the space is dominated by sophisticated arbitrage bots running custom infrastructure, private mempool access, and highly optimized smart contracts — competition has compressed average spreads significantly.
That said, profitability hasn't disappeared, it's shifted. New chains and new exchanges launch constantly, each with temporarily inefficient liquidity. Cross-chain arbitrage opportunities remain wide because bridge latency still prevents instant price convergence. Funding rate arbitrage on perpetual futures continues to offer reliable, market-neutral returns during periods of directional sentiment extremes. And liquidation arbitrage on lending protocols remains lucrative during volatile market crashes when large amounts of collateral get liquidated simultaneously.
The traders still generating consistent returns from arbitrage in 2026 share a few traits: they run their own infrastructure rather than relying on manual trading, they diversify across multiple arbitrage strategy types rather than depending on a single approach, they actively monitor new exchanges and new chains for fresh inefficiency, and they treat fee and gas optimization as seriously as opportunity detection. For most retail traders, participating profitably now means either running well-built bots or using aggregated scanning tools rather than trying to spot and execute arbitrage opportunities by hand. The traders who treat this as a full trading business, rather than casual crypto trading on the side, are the ones still pulling consistent profit from the crypto market in 2026.